
Casinos That Accept CashToCode in the UK
 Available in GB
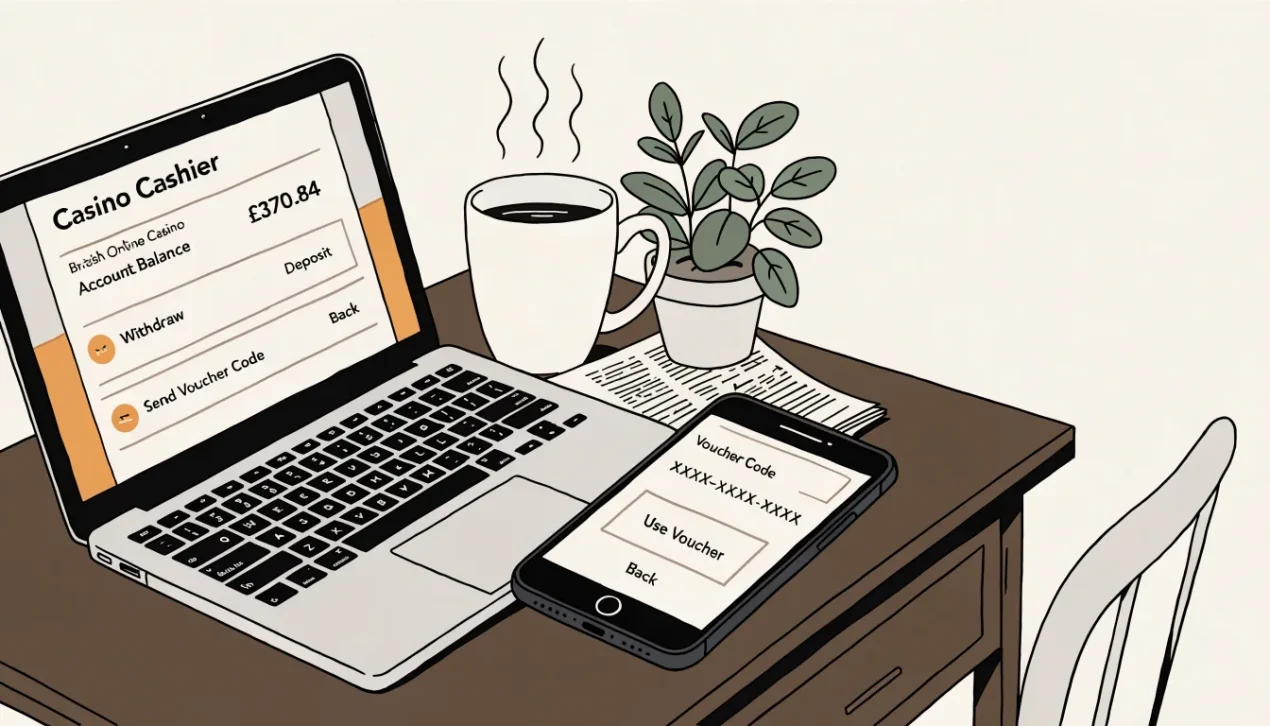
CashToCode availability must be confirmed in the operator’s cashier, while payment routes and terms shape the full transaction.
CashToCode Availability Is a Cashier Question
A casino’s payment page can look like a promise; its cashier is where a payment method becomes a usable option. That distinction matters for CashToCode in the UK. A search result, a promotional claim or a page that names the method does not, by itself, establish that a particular casino currently accepts it. Nor does it show whether the option is available to every account or for the transaction being considered.
That is not a judgement about the method or the casinos. It is a limit on what can responsibly be said: without confirmation from each operator’s own cashier, acceptance at a named site remains unconfirmed. A catalogue can look satisfyingly definite and still leave the essential question unanswered.
The practical distinction is simple. A casino may mention a payment method somewhere on its site, while the cashier presents the actual choices at the point of deposit. For CashToCode, the cashier is the place to establish whether the method is offered by that operator. If it does not appear there, an old listing or a broad claim about “CashToCode casinos” cannot turn it into an available option.
 Casinos That Accept Citadel in the UK: Payment ChecksLearn how to confirm Citadel in a casino’s own cashier, compare other deposit routes, and check how deposit and withdrawal terms fit…
 Casinos That Accept MuchBetter in the UK: What to CheckCheck whether MuchBetter appears in a UK casino cashier, and what to verify about listed payment routes, withdrawals and terms.
That applies equally to a casino described as new, the best, or suitable for Android. Those labels say nothing on their own about the payment methods currently displayed to UK customers. A mobile-friendly casino is not necessarily a CashToCode casino; an attractive bonus or games selection does not answer the cashier question either. Payment acceptance is a separate, specific claim.
The word “still” in searches about availability carries its own small history: payment pages change, and descriptions can outlive the arrangements they once described. That does not prove that a particular listing is wrong. It does mean that a past mention cannot stand in for a current check. The same caution applies when a page groups several countries together or speaks about a casino without making clear which market its payment information describes.
A useful check is deliberately narrow. Open the casino’s cashier and look for CashToCode among the methods actually offered for a UK account. If the method is listed, the display provides a stronger basis for treating it as accepted than a third-party description does. If the cashier is unclear, the operator’s own support can clarify whether the option applies to that account. A general payment-method page may offer context, but it is not a substitute for confirmation at the point where the deposit choices are shown.
This is not a claim that other payment methods are automatically available either. A specialist review lists Visa and Mastercard, but that kind of mention should not be mistaken for a guarantee that either card will work at every casino, or for every card product. Current UK availability and card eligibility need to be checked in the relevant cashier. The same principle separates a reported option from a confirmed one: naming a method is not the same as establishing its present availability.
That distinction is easy to lose because payment lists are designed to compress complexity. A row of familiar logos looks like a stable menu. In practice, the useful question is not whether a method appears in a general description, but whether the casino presents it as an available choice for the account in question. CashToCode needs that same direct confirmation; its name in a page title or an old list does not settle the matter.
Search for UK casinos accepting CashToCode and the answer may appear to be a neat list. The more careful answer is less theatrical: each casino has to be checked individually, and no operator should be treated as confirmed without cashier evidence. That is a modest standard, but payment claims concern the point at which money changes hands. Modesty is useful there.
The Payment Routes UK Casinos Actually Describe
The alternatives to CashToCode at UK casinos are not one neat substitute. They are different ways of moving money, each with its own conditions: a debit card draws on a bank account, an e-wallet adds an intermediary, a bank transfer moves funds through banking services, and a prepaid voucher keeps a deposit separate from a conventional card payment. The cashier is where those distinctions become practical. A payment method appearing on a general list does not establish that it is available to every customer or suited to every transaction.
Debit Cards
UK casinos commonly accept Visa or Mastercard.
E-Wallets
PayPal, Skrill, and Neteller offer different arrangements.
Bank Transfers
Direct banking routes that can support instant deposits.
Prepaid Vouchers
Paysafecard is a voucher used for deposits only.
Debit cards are the familiar route. UK casinos commonly accept debit cards carrying the Visa or Mastercard name, although the actual options and eligible card products should be checked in the casino’s cashier. That familiarity has social weight: the bank card is already part of ordinary household finance, so gambling deposits can look like another online purchase. Yet the label on the card is only the beginning. The relevant question is whether the particular casino accepts that card for the intended transaction.
PayPal offers a different arrangement. Rather than entering card or bank details directly into a casino payment form, a customer pays through an account held with the wallet provider. A specialist review describes PayPal as valued for speed and convenience, while also noting that a casino promotion may exclude deposits made through it. That is a useful distinction: a method can be accepted for payment without qualifying for an offer. The terms attached to a particular promotion settle that question, not the general reputation of the wallet.
Bank transfers and open banking services put the customer’s bank account closer to the transaction. A specialist review reports that these routes can support instant deposits and fast withdrawals at many sites. The wording matters: “can” is not a promise about every casino, bank, account or transaction. Availability belongs to the individual cashier, while the bank’s own process can also shape what happens. There is no need to treat a transfer as an obscure workaround; it is a direct banking route, with the familiar formality that banking tends to bring.
Prepaid vouchers work differently again. Paysafecard is a voucher bought in advance and used for deposits; it is deposit-only. That boundary makes it unlike a bank account or an e-wallet that might be available for more than one stage of play. A voucher can keep the act of paying separate from card entry, but it does not, by itself, describe a route for receiving funds back. “Payment method” is a broad label. In practice, the direction of travel matters.
Skrill and Neteller are e-wallets found at some casino sites. Their role is more conditional than a simple list of logos suggests. A specialist review describes them as often excluded from promotions, so the method’s presence in a cashier should not be confused with bonus eligibility. The wallet also introduces its own account and payment conditions; the casino’s cashier remains the place to confirm whether the route is offered and what terms apply.
These categories reflect different habits of trust. The card connects a casino transaction to a bank-issued instrument; the wallet inserts another company between the bank and the operator; the voucher begins with prepaid value; and the bank-transfer route relies on the banking system itself. None is automatically superior. Their usefulness depends on what the casino supports and on the conditions attached to the customer’s own account.
For anyone comparing CashToCode with these alternatives, the sensible comparison is between routes actually displayed by a casino, not between broad labels detached from a cashier. A card listed on a site’s general information page may still need eligibility checks. A wallet may be available but excluded from a promotion. A prepaid voucher may accept a deposit while offering no withdrawal route. Bank transfers may be described as fast at many sites without being instant in every case.
Payment menus are not promises. They are maps with local details left to the cashier. The routes described above are recognisable alternatives, but only the casino’s current payment screen can show which are open to a particular account and transaction.
Top online casinos in the UK
- SpinFormulaBonus: 550% Up To £15,000 + 550 FS · Payout speed: 1-3 business days
- SlotoSportBonus: 500% up to £ 10 200+ 777 FS · Payout speed: 1-3 business days
- Revery PlayBonus: 100% up to€1,000+ 100 FS · Payout speed: 1-3 business days
- AmunbetBonus: Join now and get 450% up to 2,700 GBP + 450 FS · Payout speed: 1-3 business days
- BeOnBetBonus: 100% up to €500 + 100 FS · Payout speed: 1-3 business days
- JetsetspinsBonus: 200% Bonus + 100 Free Spins + Free Royal Wheel · Payout speed: 1-3 business days
- NightWinBonus: £900 + 400 free spins · Payout speed: 1-3 business days
- x3betBonus: Welcome Pack 100% Up to £1.000 + 200 Free Spins · Payout speed: 1-3 business days
- ZombillionBonus: Welcome Pack 250% up to £4000 + 200 FS · Payout speed: 1-3 business days
- BritsinoBonus: Welcome Package – Get your £2,200 + 2,000 FS · Payout speed: 1-3 business days
A Deposit Is Only Half the Transaction
A payment method can appear in a casino’s deposit menu without being a route for withdrawals. The distinction matters for anyone checking whether a UK casino accepts CashToCode: seeing a deposit option would not, by itself, establish that winnings can be returned through it. Depositing and cashing out are separate parts of the transaction, governed by different checks.
UK anti-money-laundering controls commonly require a casino to return funds to the original payment source. This is part of the closed-loop approach to handling money: the route used to fund an account can shape the route available for a payout. A method described as deposit-only, or one that cannot receive withdrawals, may therefore leave a casino needing another verified way to return funds. The cashier’s payment labels are not a complete account of that process.
There is a practical consequence for CashToCode. Its presence in a deposit list, if offered by a particular casino, would not confirm withdrawal compatibility. Nor does a general claim that a casino accepts a payment method settle how that operator handles a particular account or transaction. The withdrawal rules and available routes need to be read separately, before money is sent in.
This is less a technical quirk than a feature of how gambling payments are policed. Casinos must account for where funds come from and where they go; a payout is not simply a deposit travelling backwards. Where the original route cannot receive money, or where ownership details do not match, extra checks or an alternative route may enter the picture. Paperwork has its own momentum.
Timing follows a different sequence from the initial payment. A deposit may reach an account before a withdrawal has even been reviewed. A specialist casino review describes payout processing as including the operator’s internal approval, with first withdrawals potentially taking longer while verification is completed. That qualification matters: the payment provider is not the only party controlling the clock.
Account verification can affect the pace as well. Withdrawal speed depends on the casino’s approval process and whether the account is fully verified. A pending payout may therefore reflect checks still under way rather than a failure of the payment method itself. The distinction is useful, though not always comforting.
KYC is part of this account-level scrutiny. If documents or ownership details remain outstanding, the operator may need to resolve them before releasing a withdrawal. The exact checks and processing steps vary between casinos, so a general estimate cannot substitute for the operator’s own withdrawal terms. The cashier should explain which methods are available for deposits and which can receive payouts; the withdrawal page should set out approval and verification requirements.
This also changes how a payment option should be judged. A method that is easy to use for deposits may be inconvenient if the account cannot receive withdrawals through it. Conversely, a casino may accept deposits through one route but direct payouts elsewhere under its controls. The important question is not simply whether CashToCode is accepted, but what happens after the balance is ready to leave the account.
DO
- Check the cashier for withdrawal compatibility.
- Review the operator’s specific terms.
DON’T
- Assume deposit methods work for withdrawals.
- Rely on general descriptions for availability.
For a CashToCode deposit, the responsible assumption is not that the same service will handle a cash-out. That has to be confirmed in the individual casino’s cashier and terms. If a different route is required, its ownership requirements and any additional verification can affect the process. A deposit button answers only half the question.
In the end, payout compatibility is a property of the casino’s withdrawal arrangements, not something established by the name of a deposit method. The route in, the approved route out and the account checks between them form one transaction, but they are not interchangeable. A useful distinction.
Mobile Slots, With the British Rules Still in Force
A slot played on a phone remains an online slot under British rules. The smaller screen changes the shape of the interface, not the conditions governing play. A game does not acquire a different legal character because its reels sit inside a mobile browser or an app; nor does a payment label turn it into a separate kind of slot.
That distinction matters when CashToCode and mobile slots appear together in a description. CashToCode is a way of paying, while the slot is the game. Their appearance in the same search or on the same screen does not, by itself, establish that a particular game or mobile service supports that payment route. The cashier and the game catalogue answer different questions.
The rules that matter on a phone are notably unglamorous. Autoplay is banned for online slots in Britain. Spins must also last at least 2.5 seconds. A touch-screen button may make the action feel immediate, but it cannot remove the required interval or make a sequence of spins run unattended.
That pause is not a technical inconvenience accidentally left in the machinery. It reflects a regulatory choice about how slot play should proceed: each spin must remain an event initiated by the player, rather than one step in a rolling sequence that continues without fresh action. The phone has made gambling portable; the rules resist making it frictionless.
A mobile layout can still make the game feel brisk. Reels, controls and account functions are compressed into a smaller space, and the visual movement may be designed to hold attention. But speed of presentation is not the same as permission to accelerate play beyond the prescribed minimum. The underlying rules remain in force whether a person uses a handset or another device.
The broader British framework is built around licensed remote gambling. Operators offering real-money gambling to customers in England, Scotland and Wales must hold a UK Gambling Commission licence. That requirement concerns the operator and its service, not the size of the screen. A mobile version is not a regulatory side door.
There is a social history in this insistence on sameness. Gambling once belonged to designated rooms, counters and machines; a phone carries it into the intervals of ordinary life. Regulation answers that change not by pretending the device is neutral, but by applying limits to the activity wherever it appears. The screen travels. The rules follow.
For anyone comparing mobile slots associated with CashToCode, the practical distinction is therefore simple: mobile describes how a game is accessed, while payment acceptance is a separate matter. Neither label alters the British restrictions on slot play. No autoplay; no faster spin.
Real-Money Slots Do Not Make a Payment Method Compatible
A slot described as a real-money game is one that can be played for stakes rather than only in a free-play mode. That description says something about the game, not about the cashier. It cannot establish whether a casino accepts CashToCode, whether the method appears for a particular account, or whether the cashier permits the intended transaction.
The distinction matters because the words sit close together in searches: CashToCode slots, real-money play, a casino site and a payment method can seem like one package. They are not. A game’s availability and a site’s payment options are separate conditions. Only the casino’s own cashier can show whether CashToCode is available there at that time; a real-money label on a slot supplies no answer.
In Britain, the legal setting for real-money online slots is not a decorative border around the game. Remote gambling licensees serving the British market must hold a UK Gambling Commission licence. The Gambling Act 2005 governs gambling in England, Wales and Scotland, while Northern Ireland is outside that Act’s scope. A casino’s claim that its slots accept real stakes therefore does not, by itself, establish that the site is authorised to serve customers in Great Britain.
The rules also shape what a real-money slot can offer. The maximum stake for each online slot game cycle is £5 for adults aged 25 and over, and £2 for those aged 18 to 24. The higher limit for all adults took effect on 9 April 2025. These are limits on the stake, not instructions to spend it. A game may be built around money play, but the permitted stake remains part of the British regulatory framework.
There is a further distinction between a casino game and its funding route. The Gambling Act defines a casino as an arrangement that gives people an opportunity to participate in one or more casino games; the payment method is not what makes a slot real-money. Nor does the presence of a game prove that every deposit option works with it. Payment compatibility belongs to the account and cashier, not to the reel symbols.
That separation is useful when considering claims about a CashToCode slot app, site or machine. Such wording can describe a search for a way to play, but it cannot turn a payment method into a feature of a particular game. The same is true of a free-play version: its existence would not demonstrate that real-money deposits through CashToCode are supported.
Real money, then, answers one question only: whether play involves stakes. The casino’s licensing status governs whether the operator may serve the British market, while the cashier determines which payment routes it makes available. Three separate matters.
Deposits, Withdrawals and the Credit-Card Line
The UK’s credit-card rule is a firm boundary, not a preference in a casino cashier. Since 14 April 2020, remote gambling operators have been barred from accepting credit-card payments for gambling, and the restriction remains in force. A UK-licensed casino therefore cannot accept a credit card as a way to fund a gambling deposit.
That distinction matters when a payment method’s name sounds separate from the card or account behind it. A label in a cashier does not, by itself, establish how a transaction is funded or whether it is permitted. The rule also covers credit-card payments routed through a money service business, and remote operators cannot accept wallet payments where the wallet allows credit-card funds to be used for gambling. The route cannot make a prohibited source acceptable.
CashToCode’s appearance in a payment search does not establish that a UK casino accepts it for deposits, or that it can receive withdrawals. Nor does it answer whether a transaction would involve a credit card. Those are separate questions: the casino’s cashier must show the method, and its terms must explain how the payment is treated. A method name is not a map of the money.
For deposits and withdrawals, consistent account details can help avoid a different kind of difficulty. A payment route held in the same customer’s name as the gambling account gives the operator a clearer basis for matching ownership. A mismatch can invite questions that have nothing to do with the game or the amount involved. The cleanest arrangement is often one named account used consistently for both directions, where the casino permits that route.
This does not mean every method works both ways. A deposit option is not automatically a withdrawal option, and a casino may apply its own process to the route selected. CashToCode should not be treated as a direct-withdrawal method merely because it is associated with deposits elsewhere; compatibility has to be confirmed at the particular casino.
Debit cards sit on the other side of the credit-card line, but a card’s branding alone does not settle whether a specific product or transaction is eligible. The cashier’s current terms are the relevant guide. Credit cards are excluded. Ownership still matters.
Bonuses Depend on the Payment Terms
A payment method appearing in a casino cashier does not, by itself, make a deposit eligible for a welcome bonus. The cashier answers whether a transaction can be made; the promotion’s terms answer whether that transaction counts. Those are separate decisions, even when a page puts them close together.
A specialist review has reported that PayPal can be excluded from bonus eligibility, despite its appeal as a quick and convenient way to pay. The same kind of review reports that Skrill and Neteller are offered at some sites but are often excluded from promotions. These are cautions about checking individual terms, not rules that apply to every casino. Offers and payment conditions can change, and an operator’s current promotion page is the relevant place to establish what applies.
That distinction matters when a bonus is described as available to new customers or attached to a first deposit. The label does not settle which payment routes qualify. A deposit made through an accepted method could still fall outside a promotion’s conditions. Conversely, the mere presence of a method in a list of exclusions does not tell whether every offer at that casino excludes it. The wording of the specific promotion governs.
CashToCode does not carry a bonus entitlement with it. A search for UK casinos offering a CashToCode welcome bonus, real-money slots or a bonus code cannot establish that a particular promotion exists or that CashToCode deposits qualify. Any claim about a CashToCode-specific offer needs confirmation in the operator’s live terms. A bonus code, where an offer uses one, is not proof that every deposit method is eligible.
The same care applies to free spins or other slot promotions. Their title can make the offer sound simple, while the payment clause quietly determines whether a deposit qualifies. Before making a payment in expectation of a reward, the useful details are the eligible methods, any code-entry requirement and the promotion’s own conditions. If CashToCode is not named as eligible, acceptance of the payment method alone should not be read as approval for the bonus.
A welcome offer is not a property of the cashier. It is a contract with its own small print.
Minimum Deposits and the Limits Around Them
A small-deposit search can make a single figure seem like a promise. It is not. One specialist casino review places minimum deposits in a £10–£20 range, with the amount depending on the payment method. That is a guide to the range reported there, not a fixed rule across UK casinos or a confirmed CashToCode minimum.
A claim that CashToCode can be used to deposit £5 needs more than a low figure attached to the payment name. The cashier would need to show CashToCode as an available method and state the minimum it accepts. Without both details, £5 remains an unsubstantiated expectation. A casino might set different thresholds for different payment routes, and those thresholds can change.
The same care applies when a deposit is made on a phone. A mobile cashier may display payment methods and their limits, but the device does not establish that a particular method is supported or that a smaller deposit will be accepted. Nor does the word “instant” answer the minimum-deposit question: speed and the smallest permitted amount are separate terms. The cashier is where both become concrete.
Maximums are less tidy still. A specialist review notes that limits can vary according to the payment method and account status, and may apply per transaction, per day or per month. The amount available to deposit is therefore not necessarily a single ceiling attached to the casino. Account-level restrictions can matter as well. A displayed limit is a working condition, not a universal feature of the payment brand.
For someone comparing small deposits, the useful record is the current cashier wording: the named method, its minimum, and any transaction or account limit shown before payment. If the amount changes at checkout, that difference matters more than a headline claiming a particular minimum. A low threshold can make a deposit possible; it says nothing by itself about whether that payment method can be used at that casino.
CashToCode should be treated no differently. A stated £5 minimum is meaningful only when it appears in the casino’s own current cashier for CashToCode. Without that confirmation, neither a small amount nor mobile access turns an assumed option into an available one.
Comparing Alternatives by Their Actual Cost
A payment method cannot be called the cheapest in the abstract. The cost belongs to a particular transaction: its amount, currency, route and the charges applied along the way. A specialist payment review identifies several possible sources of cost, including the casino, payment provider, bank or card issuer, currency conversion and payment network. A charge that is absent at one point may appear at another.
Understanding Costs
Total costs include the casino, provider, bank, conversion rates, and network fees.
The visible fee is only part of the calculation. A provider might show no flat charge, while converting the payment at an exchange rate that includes a spread. That difference between the market rate and the rate applied to the transaction can cost more than a clearly stated fee, according to a specialist payment review. The arithmetic is less obvious; the money still leaves the account.
The casino’s cashier is one place to start: it may disclose whether it adds a charge to a deposit. The provider’s terms may set out its own fees, while a bank or card issuer can apply separate charges. If a transaction passes through a payment network, network costs may also form part of the total. These are distinct layers, not interchangeable names for one fee.
Currency matters too. A GBP account can help avoid conversion where the casino and payment route both support sterling, but the account currency should be confirmed before the first transaction. Otherwise, an exchange spread may be applied somewhere in the chain. A low stated fee does not settle the comparison.
The useful comparison is therefore between complete costs for the same intended payment, not between slogans attached to payment brands. Check what the casino charges, what the provider takes, whether the bank or issuer adds a fee, and whether conversion or network costs apply. Then compare the resulting totals for that transaction. A different amount or currency can change the result.
That is also why no single CashToCode alternative can be labelled the cheapest for every UK casino payment. The best-value route depends on the charges attached to the specific transaction, including costs that are not displayed as a simple line-item fee. The quiet costs count.
CashToCode Does Not Establish a Casino’s GamStop Status
A payment method and a self-exclusion arrangement describe different parts of a casino. CashToCode concerns how a deposit might be made; GamStop status concerns whether an operator participates in that self-exclusion scheme. One does not establish the other. A casino advertising a particular payment route cannot be assumed to be outside GamStop, and a claim about GamStop does not confirm that CashToCode appears in its cashier.
The distinction matters because “not on GamStop” is sometimes treated as if it were a payment feature. It is not. Nor does the phrase, by itself, establish whether a site holds the licence required to serve customers in Great Britain. Remote gambling licensees selling into the British market must hold the relevant Gambling Commission licence, wherever the company is based. Offshore sites operate outside that regulatory system; payment choice does not change that position.
UKGC-licensed casinos must provide responsible-gambling tools, including self-exclusion. The regulator also requires remote operators to prompt new customers to set a financial limit before their first deposit and to make account-level limit controls accessible. Those measures are part of the operating framework, not optional features that can be sidestepped by choosing a different deposit method.
There is a difference between a site’s relationship with GamStop and the controls available within a licensed casino account. Both concern gambling safeguards, but they are not interchangeable. A CashToCode label cannot indicate how an operator handles self-exclusion, while a non-GamStop claim cannot establish that a deposit will be accepted.
The language of payment can make a casino sound like a set of doors: one method opens one entrance, another closes it. Regulation is less theatrical. Licence status, self-exclusion arrangements and financial-limit controls remain separate questions, each with its own consequences. The cashier is not a map of those protections.
For a UK-facing casino, the sensible distinction is plain: payment compatibility says nothing about GamStop participation, and neither should be treated as a substitute for understanding the operator’s regulatory position and its available safeguards. A wallet is not a way around a boundary.
What is the fastest withdrawal method for UK casinos?
PayPal, open banking services and debit cards linked to fast payout systems are generally among the quickest options. The casino’s approval process and your account verification status also affect how quickly funds arrive.
Why can a fast payout casino still delay my withdrawal?
A casino must approve the withdrawal, and first withdrawals can take longer while verification is completed. Even after approval, the payment route can affect delivery time.
What is the current minimum deposit?
The minimum deposit usually starts at £10–£20, depending on the payment method selected.
Are fast casino withdrawals guaranteed?
No. Withdrawal speed depends on the casino’s approval process, whether your account is verified and the payment method used.
Which payment methods are accepted in Great Britain?
UK casino payment options can include Visa and Mastercard debit cards, bank transfers, e-wallets and some cryptocurrencies. The available methods vary by casino and account, so check the cashier.
Are Visa and Mastercard deposits definitely debit cards?
No. Visa and Mastercard are card brands, and you should check that the particular card product is eligible in the casino’s cashier. Credit card gambling has been banned in the UK since 14 April 2020.
Related posts

UK Casino Welcome Bonuses: How Offers Work

VPN-Friendly Casinos in the UK: How Access Works
